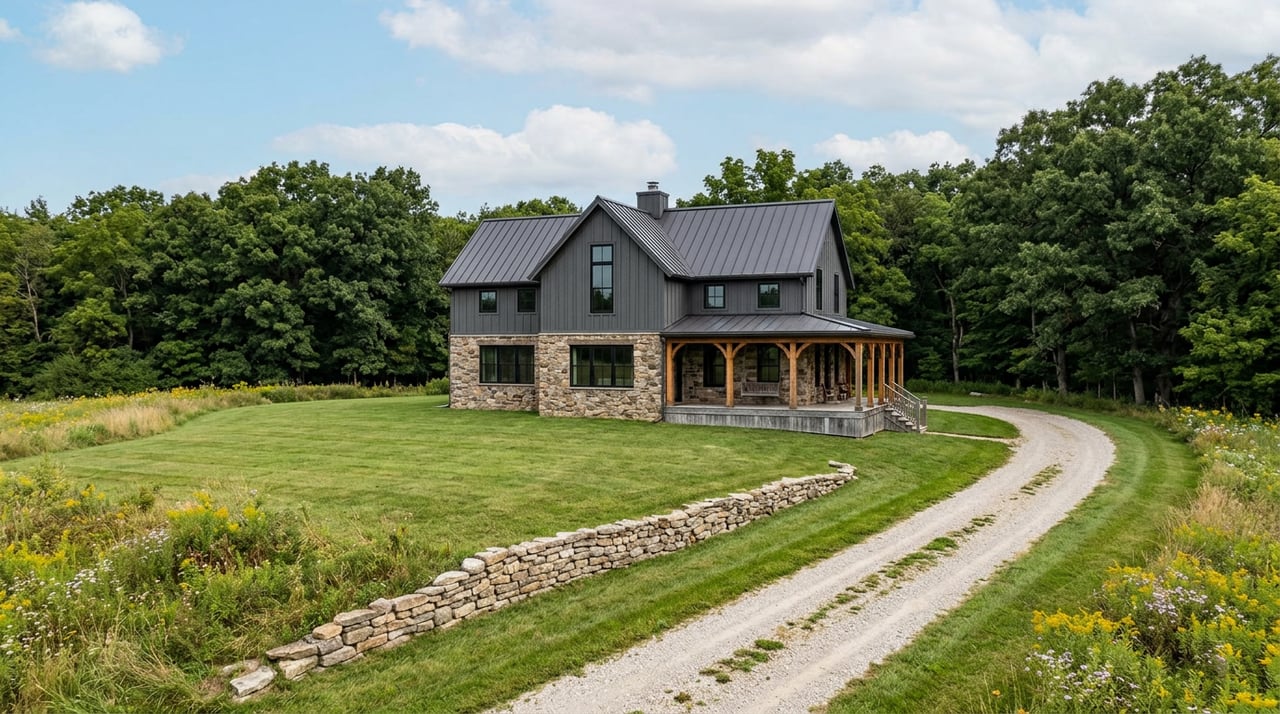
Ross County's Reappraisal Reset Every Acre's Market Value. The Farmland Tax Break Didn't Move With It.
September 17, 2026
September 17, 2026
What happens to a farm's tax bill when the county resets what every acre is worth, but the acre itself never changes?
That is not a hypothetical for anyone shopping acreage in Ross County this year. In 2025 the county completed a state-mandated mass reappraisal, and Auditor Jeff Lehner's office posted tentative 2026 values, covering tax year 2025, starting September 5, 2025. Property owners had a window that same month, the week of September 22, to sit down with the auditor's office and contest what they saw before the numbers went final. Those values are the ones now showing up on tax bills across the county. For most homeowners, that is the whole story: a new number, a new bill, done.
For anyone who owns or is buying land enrolled in Ohio's Current Agricultural Use Valuation program, it is not the whole story. CAUV lets qualifying farmland get taxed on what it produces rather than what it would sell for, and that gap between the two numbers is exactly what the state charges you for if you ever take the land out of agriculture. A reappraisal that resets market value without touching the CAUV side of the ledger does not just change what a farm owes today. It changes what converting any part of that farm will cost tomorrow.
CAUV, authorized by the Ohio Constitution and written into state law, lets land devoted to commercial agriculture get valued by soil productivity instead of sale price. Qualifying tracts typically see their taxable value cut by somewhere between 30 and 80 percent compared to a standard assessment. Ten or more contiguous acres in active commercial use qualifies automatically. Smaller tracts qualify too, as long as they generate at least $2,500 a year in agricultural income.
That is the appeal for a buyer eyeing a working farm, a hay field, or a wooded parcel with pasture attached: the carrying cost on paper looks nothing like the market price you paid for it. What often gets missed is what the program does not cover.
Even on a fully enrolled tract, the ground under the house, the barn, and any other structures gets valued at full market rate no matter what the surrounding acreage is doing. CAUV applies to the working ground, not the yard. That distinction matters the moment you start planning where a second home, a garage, or a driveway extension might go on a property that is otherwise enrolled, because that new footprint is being carved out of land that currently enjoys the tax break, not added to ground that was already excluded.
Here is the mechanism that makes this year different from an ordinary year. When land is converted out of agricultural use, the auditor removes the converted portion from CAUV and charges recoupment, which is equal to the prior three years of tax savings on that specific ground. That savings figure is the difference between the parcel's market value and its CAUV value for each of those years. It becomes a lien on the land, attached as of January 1 of the year it is levied, and it stays attached until it is paid.
Ross County's 2025 reappraisal reset the market-value side of that equation for essentially every parcel in the county, based on three years of actual sales data. The CAUV side is calculated separately, using soil productivity tables and crop-price formulas set by the Ohio Department of Taxation on its own schedule. Ohio Farm Bureau has been direct about this in its own guidance to landowners: new development and market pressure move a parcel's market value, but they do not touch its CAUV value at all. Those are two different formulas, updated on two different clocks, and a reappraisal only turns one of them.
The practical effect for anyone converting enrolled ground in Ross County going forward: the gap between what your acre is now assessed at for market purposes and what it is assessed at for CAUV purposes is not the same gap it was before 2025. On most parcels, it is wider, because the reappraisal pulled market values up while the CAUV figure sat where the state's separate formula left it.
| Part of the parcel | How it's valued | What happens if you convert it |
|---|---|---|
| Land under the house, barn, and other structures | Full market value, whether or not the rest of the tract is enrolled | Nothing changes; it was never in CAUV |
| Active cropland or pasture currently enrolled | Soil-based agricultural value, set by the state | Stays as-is as long as commercial ag use continues |
| Acreage you convert to a homesite, driveway, pond, or other non-farm use | Reverts to market value the year the use changes | Triggers recoupment: the prior three years' tax savings on that portion, billed as a lien |
There is a second layer here that cuts against the reader's first instinct, which is to assume the state is making CAUV more forgiving right now. It is, just not on Ross County's timeline. The Department of Taxation's 2026 update lowers CAUV values by roughly 5 percent on average and, for the first time, values qualifying permanent pastureland at the same minimum rate as woodland, a change Ohio Farm Bureau has pushed for years to win. That update applies to the group of counties going through reappraisal in 2026.
Ross County's mass reappraisal landed a year earlier, in 2025, which means the county's CAUV figures for this cycle were set under the older tables, before the pastureland change took effect. A buyer looking at a Ross County property with permanent pasture is not getting the benefit of that more favorable valuation this cycle. The next chance for that relief to reach Ross farmland arrives on the state's normal update schedule, not this year.
If you are the one planning to build on part of an enrolled tract, here is the order of operations that keeps the number from surprising you at closing or the year after:
Does converting one homesite trigger recoupment on the whole farm? No. Conversions are handled tract by tract. Only the acreage that actually changes use loses CAUV status and generates a charge. The rest of an enrolled parcel keeps its agricultural valuation as long as it stays in qualifying use.
If I buy land that's already enrolled, do I inherit the recoupment risk? The lien follows the land, not the person who caused the conversion. Buy enrolled acreage, convert part of it later, and the charge attaches to your parcel regardless of who worked the ground before you. That is exactly why the responsibility needs to be spelled out in the purchase agreement before closing, not discovered afterward.
Does the county's 2025 reappraisal change my parcel's current CAUV value? The reappraisal reset market values, which is one side of the recoupment formula. Your parcel's CAUV value is set separately, on the state's own soil-based schedule, so the two numbers do not move together automatically. That mismatch is precisely what widens or narrows what you would owe if the land ever changes use.
Acreage in Ross County rarely comes with a tidy answer on questions like this, and the paperwork rewards buyers who ask before they sign rather than after. If you're evaluating a property with working ground attached, whether you're planning to farm it, hold it, or eventually build on part of it, Brandon Emmanuel can help you read the parcel record the way an auditor does before it becomes a surprise on next year's bill. Let's connect before the offer goes in.
Stay up to date on the latest real estate trends.
Get assistance in determining current property value, crafting a competitive offer, writing and negotiating a contract, and much more. Contact me today.